Removal of Credit Card Surcharges: What Small Businesses Need to Know and How to Prepare
Learn what the removal of credit card surcharges means for small businesses, how it impacts pricing and margins, and practical steps to prepare your business for change.
Published 1 April 2026
Removal of credit card surcharges is now a confirmed change for Australian small and medium‑sized businesses. Following a decision by the Reserve Bank of Australia, credit and debit card surcharges will be removed from 1 October 2026, marking a significant shift in how businesses recover merchant fees.
While surcharges have traditionally helped offset payment processing costs, increasing regulatory scrutiny and consumer expectations for transparent pricing are driving a move toward simpler, all‑inclusive pricing models. For businesses that currently rely on surcharges, this change will require a reassessment of pricing structures and cost management strategies.
As the transition approaches, businesses need to understand the implications, evaluate their current pricing models, and prepare for a future where transaction costs are absorbed into everyday operations rather than passed on at checkout.
Removal of Credit Card Surcharges and Its Impact on Businesses
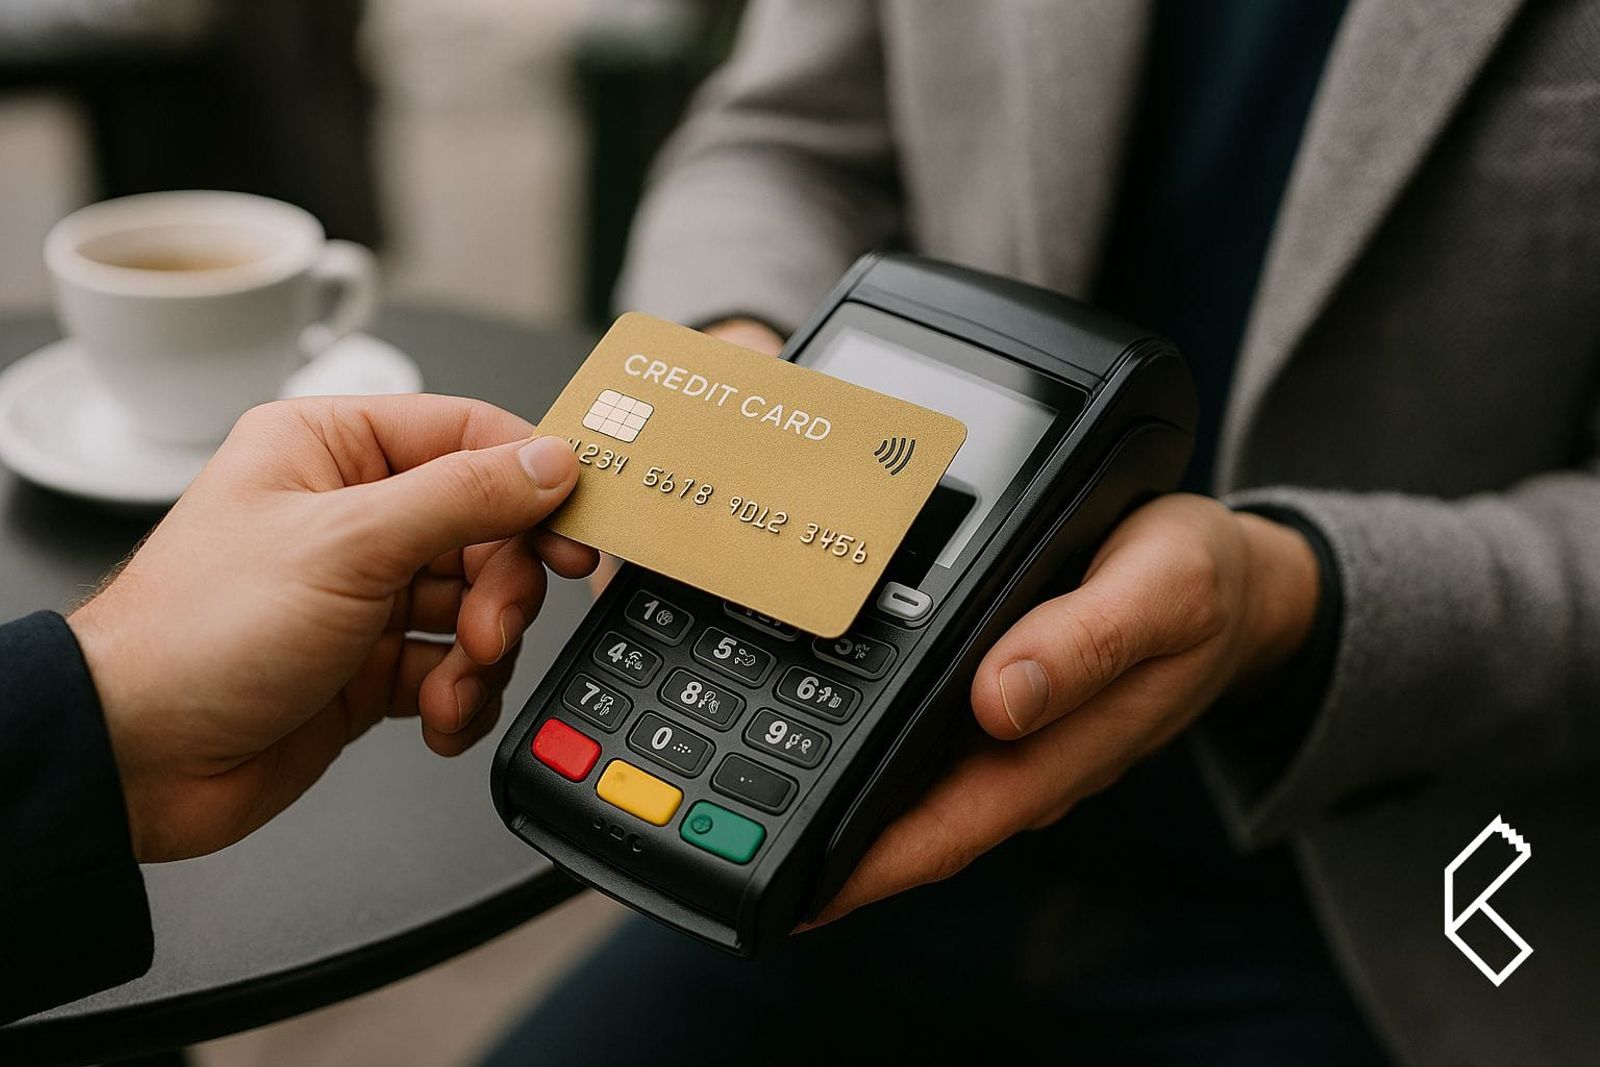
The removal of credit card surcharges refers to the elimination of additional fees that businesses currently charge customers for paying with credit or debit cards. From 1 October 2026, businesses will no longer be permitted to apply surcharges to eftpos, Visa, or Mastercard transactions.
These surcharges have traditionally been used to pass payment processing costs directly to customers. With the confirmed regulatory changes and increasing demand for transparent pricing, businesses will need to incorporate these costs into their base pricing rather than itemizing them at checkout.
For small businesses, this change can have a meaningful impact across several areas:
- Profit margins may tighten as transaction costs are absorbed internally
- Pricing strategies may need to be recalibrated to remain competitive
- Customer experience may improve due to clearer, upfront pricing
- Payment systems may need reassessment to optimise fees and efficiency
Customers increasingly prefer straightforward pricing without unexpected add-ons. This shift places pressure on businesses to simplify their pricing models while maintaining profitability.
What’s Changing from 1 October 2026
From 1 October 2026:
- Businesses will no longer be allowed to charge surcharges on eftpos, Visa, or Mastercard payments
- Merchant interchange fee caps will be reduced
- Card payment costs must be absorbed or built into pricing
These reforms are designed to improve price transparency for consumers while reducing overall payment costs for businesses over time.
Why This Matters for Small Businesses
Small businesses often operate with tighter margins than larger enterprises, making the recovery of payment processing fees an important consideration. The removal of surcharges means these businesses must adapt by finding ways to absorb or offset these costs without negatively impacting financial stability.
Failing to prepare could lead to:
- Reduced profitability
- Inaccurate pricing models
- Cash flow challenges
- Inefficient cost tracking
Proactively planning for these changes can help businesses maintain control over their financial outcomes while continuing to deliver value to customers.
Key Considerations When Surcharges Are Removed
- Pricing Structure Adjustments Businesses may need to transition to all-inclusive pricing. This involves embedding payment processing costs into the overall price of goods or services rather than charging them separately. Careful modelling is essential to ensure margins remain sustainable.
- Merchant Fee Analysis Not all payment providers charge the same rates. Reviewing your current merchant services and comparing alternatives can help reduce overall transaction costs. Even small percentage differences can significantly impact profitability over time.
- Accounting and Bookkeeping Changes Without surcharges as a separate income stream, transaction fees should be recorded as expenses. This requires accurate bookkeeping to ensure financial reports reflect true profitability and cost structures.
Working with professional bookkeeping support such as iKeep can help ensure these changes are tracked correctly and consistently.
- Regulatory Compliance With the formal removal of surcharges, businesses must ensure their pricing and payment practices align with both current requirements and upcoming regulatory changes. Businesses should ensure they are compliant with current guidelines to avoid penalties or reputational risks.
Prepare Your Business
Preparing for the removal of credit card surcharges requires a proactive and structured approach. Here are practical steps businesses can take:
Conduct a Pricing Review Analyze your current pricing model and determine how much of your margin is dependent on surcharge recovery. Identify opportunities to adjust base pricing without losing competitiveness.
Audit Payment Processing Fees Review your current payment providers and assess the fees associated with each. Consider negotiating better rates or exploring alternative providers that offer more favorable terms.
Evaluate Alternative Payment Options Encourage cost-effective payment methods where appropriate. Some businesses may benefit from promoting lower-cost payment channels to reduce overall fees.
Update Financial Systems Ensure your accounting systems are set up to categorize payment processing fees as expenses. Accurate reporting will help you understand the true cost of transactions and maintain visibility over margins.
iKeep supports businesses by reviewing pricing models, ensuring merchant fees are correctly recorded as expenses, and maintaining clear visibility over margins and cash flow during the transition.
Communicate Pricing Changes Clearly If pricing adjustments are required, communicate them transparently to customers. Clear messaging helps maintain trust and avoids confusion around price changes.
Monitor Cash Flow Regularly Changes in fee structures can impact cash flow. Regular monitoring ensures you can respond quickly to any shortfalls or unexpected trends.
Internal Financial Visibility Is Key
One of the most important aspects of preparing for surcharge removal is maintaining strong financial visibility. Understanding your margins, cost drivers, and transaction expenses allows you to make informed decisions rather than reactive ones.
This is where ongoing financial support becomes valuable. Services such as bookkeeping, reporting, and advisory support from iKeep can help businesses:
- Track expenses accurately
- Analyze profitability by product or service
- Forecast cash flow more effectively
- Identify cost-saving opportunities
- Maintain compliance with financial regulations
How Businesses Can Stay Competitive
While the removal of credit card surcharges may present challenges, it also creates opportunities for businesses to differentiate themselves through pricing transparency and improved customer experience.
Businesses that adapt early can benefit from:
- Stronger customer trust due to clearer pricing
- Streamlined checkout experiences
- More consistent pricing strategies
- Improved financial planning and forecasting
Rather than viewing surcharge removal as a limitation, it can be approached as an opportunity to refine operations and strengthen financial management practices.
Final Thoughts
The removal of credit card surcharges signals a broader shift toward simplicity and transparency in how businesses price their goods and services. While this change may require adjustments to pricing models, accounting processes, and payment strategies, it also encourages more efficient and customer-friendly business practices.
By reviewing your pricing, analyzing your costs, and strengthening your financial systems, your business can adapt smoothly to this evolving landscape. Partnering with experienced financial support providers like iKeep can further ensure that your business remains financially resilient, compliant, and well-prepared for future changes.
Taking action now will place your business in a stronger position to maintain profitability, improve transparency, and continue delivering value to your customers in a changing payments environment.
 100+
100+ accountants trust iKeep
Want books you can actually trust?
Reading is a good start. Let iKeep keep your books complete, current and accurate — so the numbers are always right.
More on Bookkeeping
New Financial Year Checklist: 5 Smart Moves After EOFY
New financial year checklist for Australian small businesses: discover 5 practical steps to review performance, improve cash flow and plan for the year ahead.
Read more10 Things Disruptive Founders do Better Than Anyone Else
Imagination, persistence and integrity are vital, but the best founders I know possess a unique DNA. Here are some habits of successful entrepreneurs.
Read more$15.3 Million in Penalties for Sushi Restaurant Chain and Director for Serious Breaches
A director and CEO of a group of four sushi restaurants, operating across New South Wales, the ACT, and the Northern Territory (Sushi Bay Group), has been hit with a $1.6 million penalty by the Federal Court of Australia
Read more